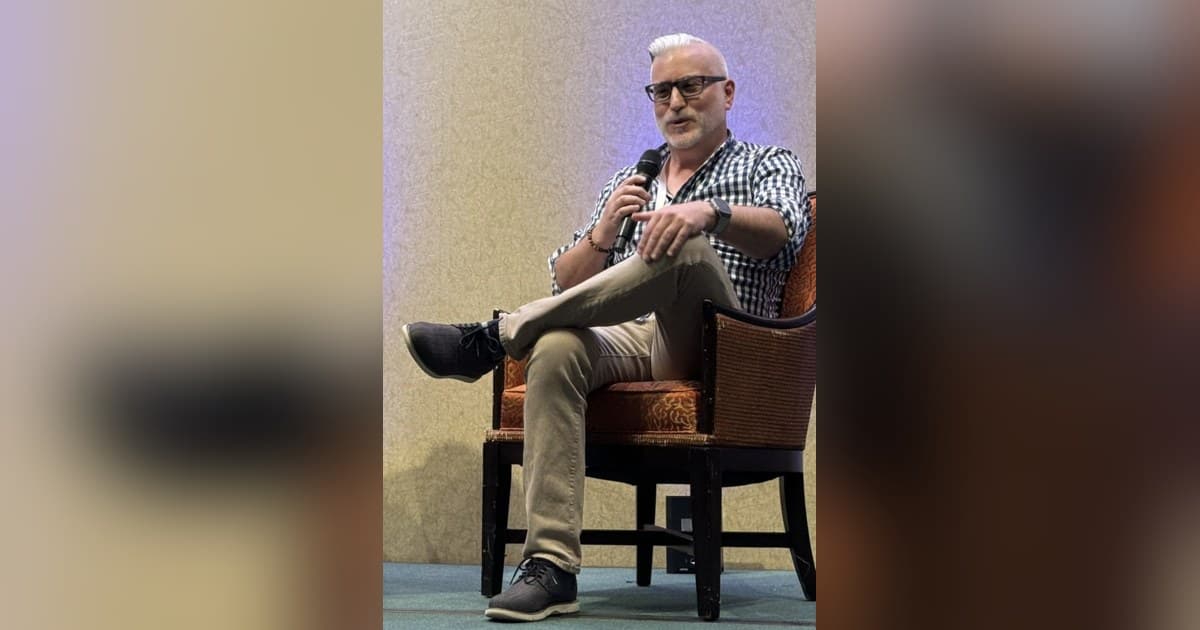
Daniel Kaufman, founder and CEO of Kaufman & Company, said the wave of commercial real estate retrades that followed the Federal Reserve's September rate increase is separating capital that can close from capital that cannot, and that family offices investing their own money should be ready to step into that gap.
The Fed raised its benchmark rate by a quarter percentage point on Sept. 16, and minutes released Oct. 7 showed most officials believe another increase would likely be appropriate by year end. Since then, The Wall Street Journal and trade outlets including CRE Daily and Citybiz have reported buyers pressing to renegotiate deals signed earlier in 2026, with some threatening to walk away. Trepp data cited in that coverage show 11.42% of CMBS loans were with special servicers in August, the highest share since February 2013.
"A retrade is a buyer telling a seller the deal was really a bet on the rate," Kaufman said. "When the rate moves, the price moves, and everyone downstream waits. The sellers, contractors and towns counting on those projects carry that uncertainty. We invest our own capital, so our underwriting has to work without assuming the next Fed decision goes our way."
The significance extends beyond individual transactions. Retrades unsettle the pipeline of projects already in motion, and the uncertainty they generate is borne by parties who did not sign the original contract: builders awaiting a closing, municipalities counting on development, and, in housing, the eventual residents of units not yet built. Kaufman said the moment favors long-term owners over buyers whose returns depend on a narrow financing window, particularly in housing, where a stalled closing can push back construction and leave homes unbuilt.
"This is when family office capital should earn its keep," Kaufman said. "We are not looking to win by grinding down a seller who negotiated in good faith. We want to be the partner people can count on at the closing table, because on a housing deal a delay is not a line item; it is fewer homes for the people who need them."
Kaufman & Company invests only its own capital and does not raise outside funds, a structure the firm presents as the source of its ability to close without depending on the next rate decision. Its operating companies span housing development, design and construction, real estate consulting and venture investment, and this month the company announced BUILD 2030, a national initiative coordinating its housing, real estate and AI infrastructure work. The platform, described at thekaufmanco.com, represents more than $2 billion in project value and more than 10,000 housing units across more than 25 years of building, lending and investing.
For readers in real estate, construction and housing policy, the message is that financing certainty is becoming a competitive advantage in its own right. With most Fed officials signaling another possible increase by year end, deals priced on the assumption of stable rates remain exposed to further retrading, and sellers may increasingly weigh a buyer's capacity to close as heavily as the headline price.
