Real estate investors who wait until the final weeks of the tax year to reconstruct their property spending risk losing the detail that determines how those costs are treated, according to CostSegRx, an engineering-based cost segregation firm. The company said the last-minute dig through inboxes and bank statements is where owners tend to lose the details that shape their depreciation.
“Property owners should really document all of their capital improvements and expenses throughout the year,” said Brian Kiczula of CostSegRx. “It’s not just at the year-end.” The goal, the firm said, is not a perfect filing cabinet but a clear record of what work was done, when it was done, and what it cost.
The distinction matters because capital improvements and repairs are treated differently for tax purposes. When a CPA or cost segregation professional reviews an owner’s spending, they typically apply the BAR test, which asks whether each cost is a betterment, an adaptation, or a restoration. Costs meeting one of those definitions generally must be capitalized and depreciated over 27.5 years for residential rental property, 39 years for commercial property, or shorter lives of 15, 7, or 5 years. Costs that do not meet the test usually fall into repairs and maintenance, which can be deducted in the year they are incurred. Without records, there is no reliable way to tell which bucket a cost belongs in.
In CostSegRx’s experience, the gap almost always comes down to individual receipts and a clear description of the work performed. Some owners keep every receipt in a cloud folder and track each improvement, with dates, in a spreadsheet. Others know roughly how much they spent over the year but cannot say how that money was divided among new flooring, windows, lighting, or a bathroom remodel. Many contractors bill in lump sums without breaking out what each part of the project cost. For owners in that position, CostSegRx uses construction cost estimating, rebuilding the contractor’s costs from the owner’s description and images of the property so each improvement can be classified.
Timing adds another layer for owners who buy and renovate in the same year. If renovations were finished before the property went into service, the original cost segregation study may need to be adjusted. If the property went into service first and a major remodel followed months later, the owner’s tax preparer would typically receive two separate fixed asset schedules, one for the acquisition and one for the remodel. The same approach applies when a property is bought one year and renovated the next, a pattern CostSegRx sees often with hotels.
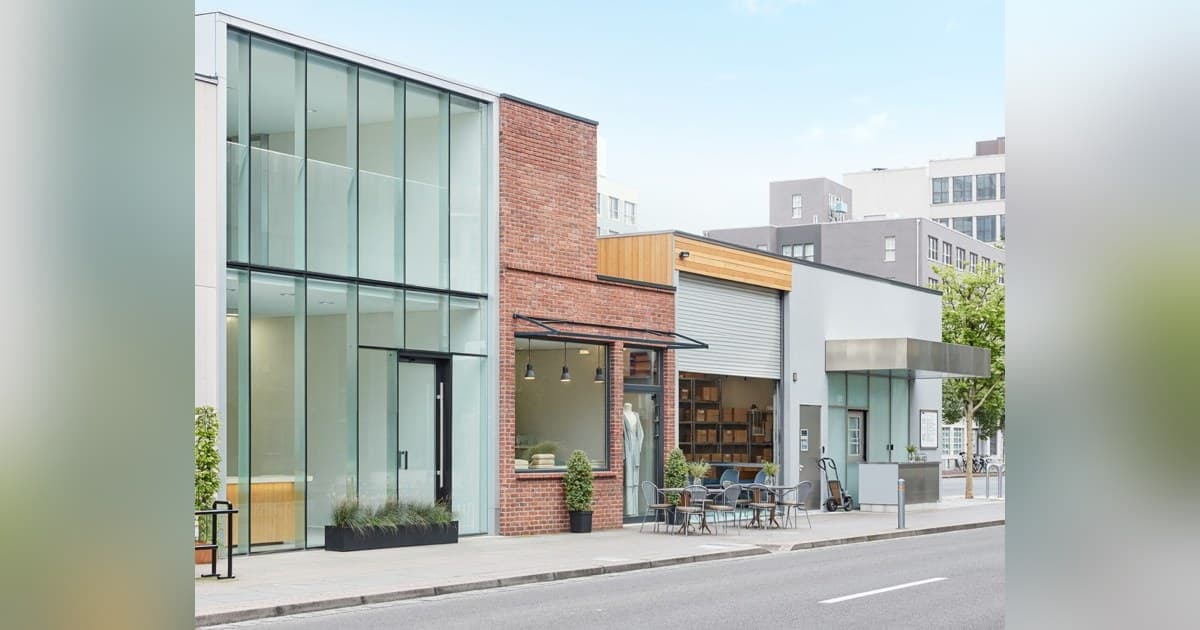
Disorganization is common among landlords, and the firm said it is usually the rule rather than the exception. That does not mean the opportunity is lost. CostSegRx recently completed a study on a multi-year renovation of three buildings—a restaurant, a boutique bed and breakfast, and a group of shops—where the owner lacked the original construction data and the team still produced a quality study. The practical takeaway is to stop treating documentation as a year-end task: keep records as work happens, share them with a CPA, and ask early how renovations will be classified.
